Supplier screening
We sort the supplier base by twelve-month spend, so it is clear which suppliers fall in scope, which need the enhanced checks and where the effort should go first.
FOR ACCOUNTING & TAX FIRMS · UAE · FTA DECISION NO. 13 OF 2026
We do the supplier checks, chase the documents and prepare the files. You manage every client in one partner portal and keep the relationship, the advice and your margin.
Already registered? Sign in · Prefer to talk first? Send us a message
See a sample verification file
Need this for your own business? Check your estimated costs.
Dubai-basedWorks under your brandWholesale partner ratesStart with one client
THE FIRST STEP
Choose one client and a defined group of suppliers. We agree the checks, fee and delivery date before starting, then carry out the work and provide the supporting files.
You can assess the quality before deciding whether to use us for more clients. There is no ongoing commitment.
No call needed: register your firm, accept the Partner Agreement and add your first client in the portal. Prefer to talk first? Send us a message and we call you — free of charge.
A fixed fee for the agreed first scope, confirmed in writing before any work starts. No ongoing commitment.
We set the date once the scope and the available records are clear, so the timeline fits the actual work.
Not sure how much work is involved? We can first review the available supplier and purchase data to help define the scope.
WHAT WE DO
We do the checking, chase what is missing and keep the evidence file. The exact scope is agreed with you before we start.
We sort the supplier base by twelve-month spend, so it is clear which suppliers fall in scope, which need the enhanced checks and where the effort should go first.
Trade licence, who is authorised to act for the company, whether there is a real place of business, and the supplier risk indicators named in the decision. We also keep track of when a supplier is due to be checked again.
We apply the agreed checks to the supplies in scope. Where information is missing or something does not fit, such as a payment to a third party or a foreign account, a price that looks out of line or an invoice for work outside the supplier’s licence, we investigate it and record the outcome.
What was checked, which documents were used, what did not fit and how it was resolved, who reviewed it and when. If anyone later asks what was done, the file shows it.
SAMPLE VERIFICATION FILE
The file shows what was reviewed, which evidence was used, what questions came up and how they were resolved. This is what your team receives for each supplier in scope.
Corporate information
Enhanced checks
Supplier indicators
Resolved exception
ResolvedInvoice description required activity clarification
A service description on two invoices did not clearly align with the primary activity visible in the initial licence record.
Illustrative example using fictional data. Fields and layout can be adapted to your firm’s working papers.
WHO YOU WORK WITH
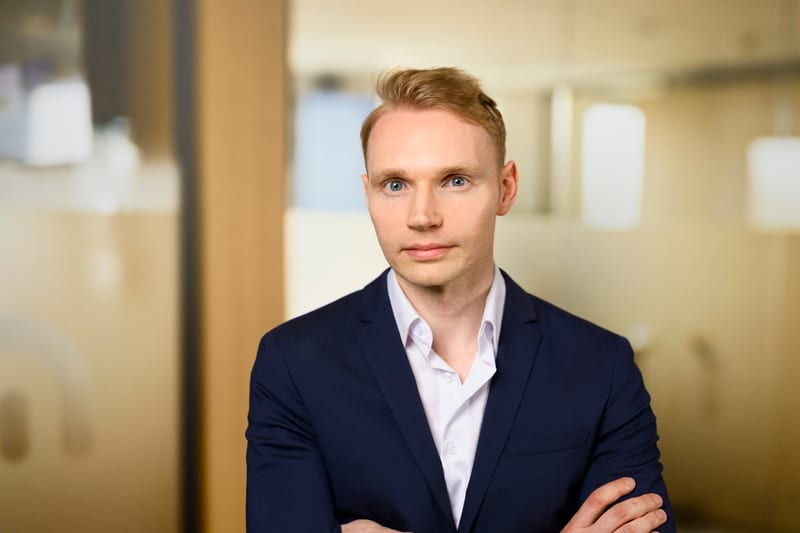
I’m Rainier van Dam. My background is in banking and real-estate finance. I’m CAMS-certified and previously led a financial crime team of 15 analysts within a regulated institution under AML supervision.
That experience is directly relevant to this work: reviewing counterparties, investigating transactions and recording the reasons behind a decision. You deal with me directly, from agreeing the scope to reviewing the output.
WHITE-LABEL DELIVERY
Your existing tax arrangements stay in place. We provide the verification work and supporting records. VAT advice, filings and decisions on input tax remain with your tax team or adviser.
YOUR FIRM
You keep control of the engagement.
NEXT HORIZONS
We handle the operational verification scope agreed with you.
Confidentiality, data access and conflict arrangements are agreed before any client information is exchanged. More on how we work with firms: Partners.
WHO WE WORK WITH
TAX AND ACCOUNTING FIRMS
We work behind your firm, under your brand if you prefer. You keep the client, the advice and the FTA-facing role, and you set the price to your client. Start with one client and expand if it works for you.
Discuss a White-Label PartnershipBUSINESSES WITH A LARGE SUPPLIER BASE
Trading, construction, hospitality, logistics and real estate groups often deal with hundreds of suppliers and one finance team. We take the checking off that team’s desk and work alongside your tax adviser, not instead of them.
Businesses can see their fixed package price straight away and order online.
Check my estimated costsTHE RULES IN BRIEF
FTA Decision No. 13 of 2026 sets out how suppliers, and the supplies received from them, are verified before input VAT is deducted. It was issued for the purposes of Article 54 bis of the VAT Law and has applied since 1 October 2026.
Supplies below AED 10,000 (excluding VAT) can fall outside the verification measures under the conditions in Article 6. That exception no longer applies once supplies from the same supplier exceed AED 100,000 over the previous twelve months, or are expected to over the next twelve. Where supplies from one supplier exceed AED 375,000 over the same periods, enhanced verification applies, including a confirmation from a UAE bank and a review of public information about the supplier. Article 5 also requires a written policy setting out who performs, reviews and supervises the checks.
How the decision applies to a particular client is for that client’s tax adviser to judge. Where your firm decides the verification is needed, we provide the capacity to carry it out and document it.
For the detail, see FTA Decision No. 13 of 2026, explained and our supplier verification checklist.
For one company with a small supplier base, that may still be manageable internally. Across dozens or hundreds of VAT clients, it quickly becomes an operational exercise: collecting evidence, checking suppliers, reviewing transaction-level indicators, following up exceptions and retaining a file that shows what was checked and why.
Identity, business information, authorised representation, business presence and the relevant supplier risk indicators.
Additional checks where the applicable conditions are met, including required banking evidence and reliable public-source information.
Commercial rationale, activity consistency, unusual values or volumes, payment arrangements, intermediaries and other relevant transaction circumstances.
HOW THE WORK IS DONE
We receive the agreed supplier master, accounts-payable data and available supporting records.
Supplier and transaction data is assessed to determine the verification work required and identify relevant thresholds.
We review the supplier identity, business information, representation, presence and other required supplier-level information.
In-scope supplies are checked against the agreed criteria, including activity, value, payment arrangements and commercial circumstances.
Where evidence is missing or something does not fit, the case goes to an analyst, who follows it up and records the outcome.
Checks, evidence, sources, explanations and review actions are retained in the verification file.
Changes, outstanding items and future verification requirements remain visible rather than disappearing after onboarding.
If a case cannot be cleared from the available evidence, we flag it. Your tax team decides what happens after that.
PORTFOLIO VIEW
The partner view brings the supplier population, outstanding evidence, enhanced reviews and open exceptions into one place, so it is clear what is complete, what still needs work and where the tax team may need to make a decision.
| Supplier | 12m spend | Verification level | Status | Open items | Last activity |
|---|---|---|---|---|---|
| Crescent Technical Services LLC | AED 428,500 | Enhanced | Cleared with rationale | 0 | 19 Aug 2026 |
| Harbour Industrial Supplies LLC | AED 312,840 | Standard | Verified | 0 | 18 Aug 2026 |
| Bluewater Facility Support LLC | AED 188,200 | Standard | Evidence requested | 2 | 19 Aug 2026 |
| Northgate Equipment Trading LLC | AED 94,650 | Standard | In review | 1 | 20 Aug 2026 |
| Atlas Business Services FZE | AED 63,900 | Standard | Exception review | 2 | 20 Aug 2026 |
Illustrative workflow and fictional data. Fields and reporting can be adapted to the partner’s agreed process.
EXCEPTION REVIEW
Every supply in scope goes through the agreed checks. Where evidence is missing, details are inconsistent or the circumstances are unusual, the case moves to an exception queue for an analyst to follow up.
| Case | Supplier | Issue | Value | Status | Owner |
|---|---|---|---|---|---|
| EX-0261 | Bluewater Facility Support LLC | Payment beneficiary mismatch | AED 84,300 | Awaiting evidence | Analyst |
| EX-0262 | Atlas Business Services FZE | Activity clarification | AED 23,750 | Analyst review | Analyst |
| EX-0263 | Northgate Equipment Trading LLC | Unusual transaction value | AED 155,400 | Referred to partner | Tax team |
| EX-0258 | Crescent Technical Services LLC | Activity clarification | AED 47,200 | Resolved | QA complete |
Illustrative workflow and fictional data.
OUTPUT
The output is designed so that the partner can understand what was done without having to reconstruct the work later.
Checks completed, result and date.
Documents and sources used during verification.
Items that required additional information or analyst review.
A short explanation wherever a case needed follow-up or judgement.
A structured file that can be retained with the partner’s own working papers.
TECHNOLOGY SUPPORT
Parts of the workflow run on tooling from our separate software business, Next Horizons Software: data structuring, document extraction, consistency checks, threshold monitoring and evidence organisation. Analyst review, exception handling, escalations and QA remain human work within the Next Horizons engagement.
View Next Horizons SoftwarePARTNER MODEL
The commercial model is designed for firms that already have VAT clients and do not want to recruit, train and manage a separate verification operation before they know how much demand there will be.
The alternative is building this internally: recruitment, training, a review framework, tooling and QA, all as a permanent cost before the demand is proven. Working with us turns that into a variable cost with a defined scope, starting from a single client.
PARTNER TERMS
Fees are agreed per client once the scope and the available records are clear.
COMMON QUESTIONS
No. Under this service, Next Horizons provides operational verification and compliance support. VAT advice, input-tax decisions, VAT filings and FTA representation remain with the partner firm or the client’s appointed tax professional.
No. We also work directly with businesses, alongside their tax adviser, who keeps the VAT position and any decisions on input tax. Businesses order a fixed-price package online on our homepage. Partner firms work on separate wholesale rates in the partner portal.
The intake call costs nothing. The first piece of work is a fixed fee for an agreed scope, confirmed before we start. There is no ongoing commitment.
Yes. The exact model is agreed with the partner. Next Horizons can work behind your firm’s process and reporting structure.
Only where that has been agreed with you. In a fully white-label engagement, your firm can remain the sole commercial contact.
This depends on scope, but usually starts with the supplier master, relevant accounts-payable or transaction data and the supplier evidence already held by the client. We don’t need any client data until the scope and confidentiality arrangements are agreed.
We document the issue, request or review the relevant evidence and record the outcome. If the matter requires a tax decision, it is referred back to your team.
Yes. Where practical, the workflow and output can be adapted to the partner’s existing process so that the service does not sit separately from the rest of the client file.
Yes. Larger portfolios are scoped separately, because the amount of evidence collection and manual review can vary considerably from one client to the next.
No. The screens use fictional data to illustrate how the work and the evidence are organised.
START A CONVERSATION
Briefly describe the client or the supplier base you have in mind. You will get a personal reply within one business day with a suggested scope. There is no need to send any client data at this stage.